What glass insurance actually covers, which conditions trigger bicycle theft, and where insurers cut corners.
Is your ceramic cooktop cracked or your bicycle stolen, and your insurance company won't pay? With glass and bicycle damage claims, details in the fine print often make all the difference. What exactly constitutes glass and what conditions must be met for a bicycle theft claim are frequently at the heart of the dispute. Rogert & Ulbrich will review your policy terms and assess your claim.
Why small divisions often cause trouble
Glass, bicycle, and similar supplemental insurance policies are generally considered straightforward. That's precisely why it's worth taking a close look at the terms and conditions. What is and isn't covered is often determined by clauses, definitions, and obligations that are frequently overlooked. If a claim arises, the insurer will rely on these very details.
From his previous work on the insurance side, lawyer Dario Kovac knows that many rejections in these sectors are contestable. Often, claims fail due to a narrow interpretation that doesn't hold up under closer scrutiny.
Your supplemental insurance isn't paying? Don't accept the explanation without checking it, because a Insurer's refusal to pay benefits is often just a matter of interpretation.
What glass insurance actually covers
Glass insurance covers breakage of insured glass and glass-ceramic surfaces. Typically, the insurance covers breakage, meaning shattering or shattering, but not a mere scratch or superficial damage. The definition of "glass" in the policy terms is broader than many people realize.
- Window and door glazing: The classic case, usually easily insured.
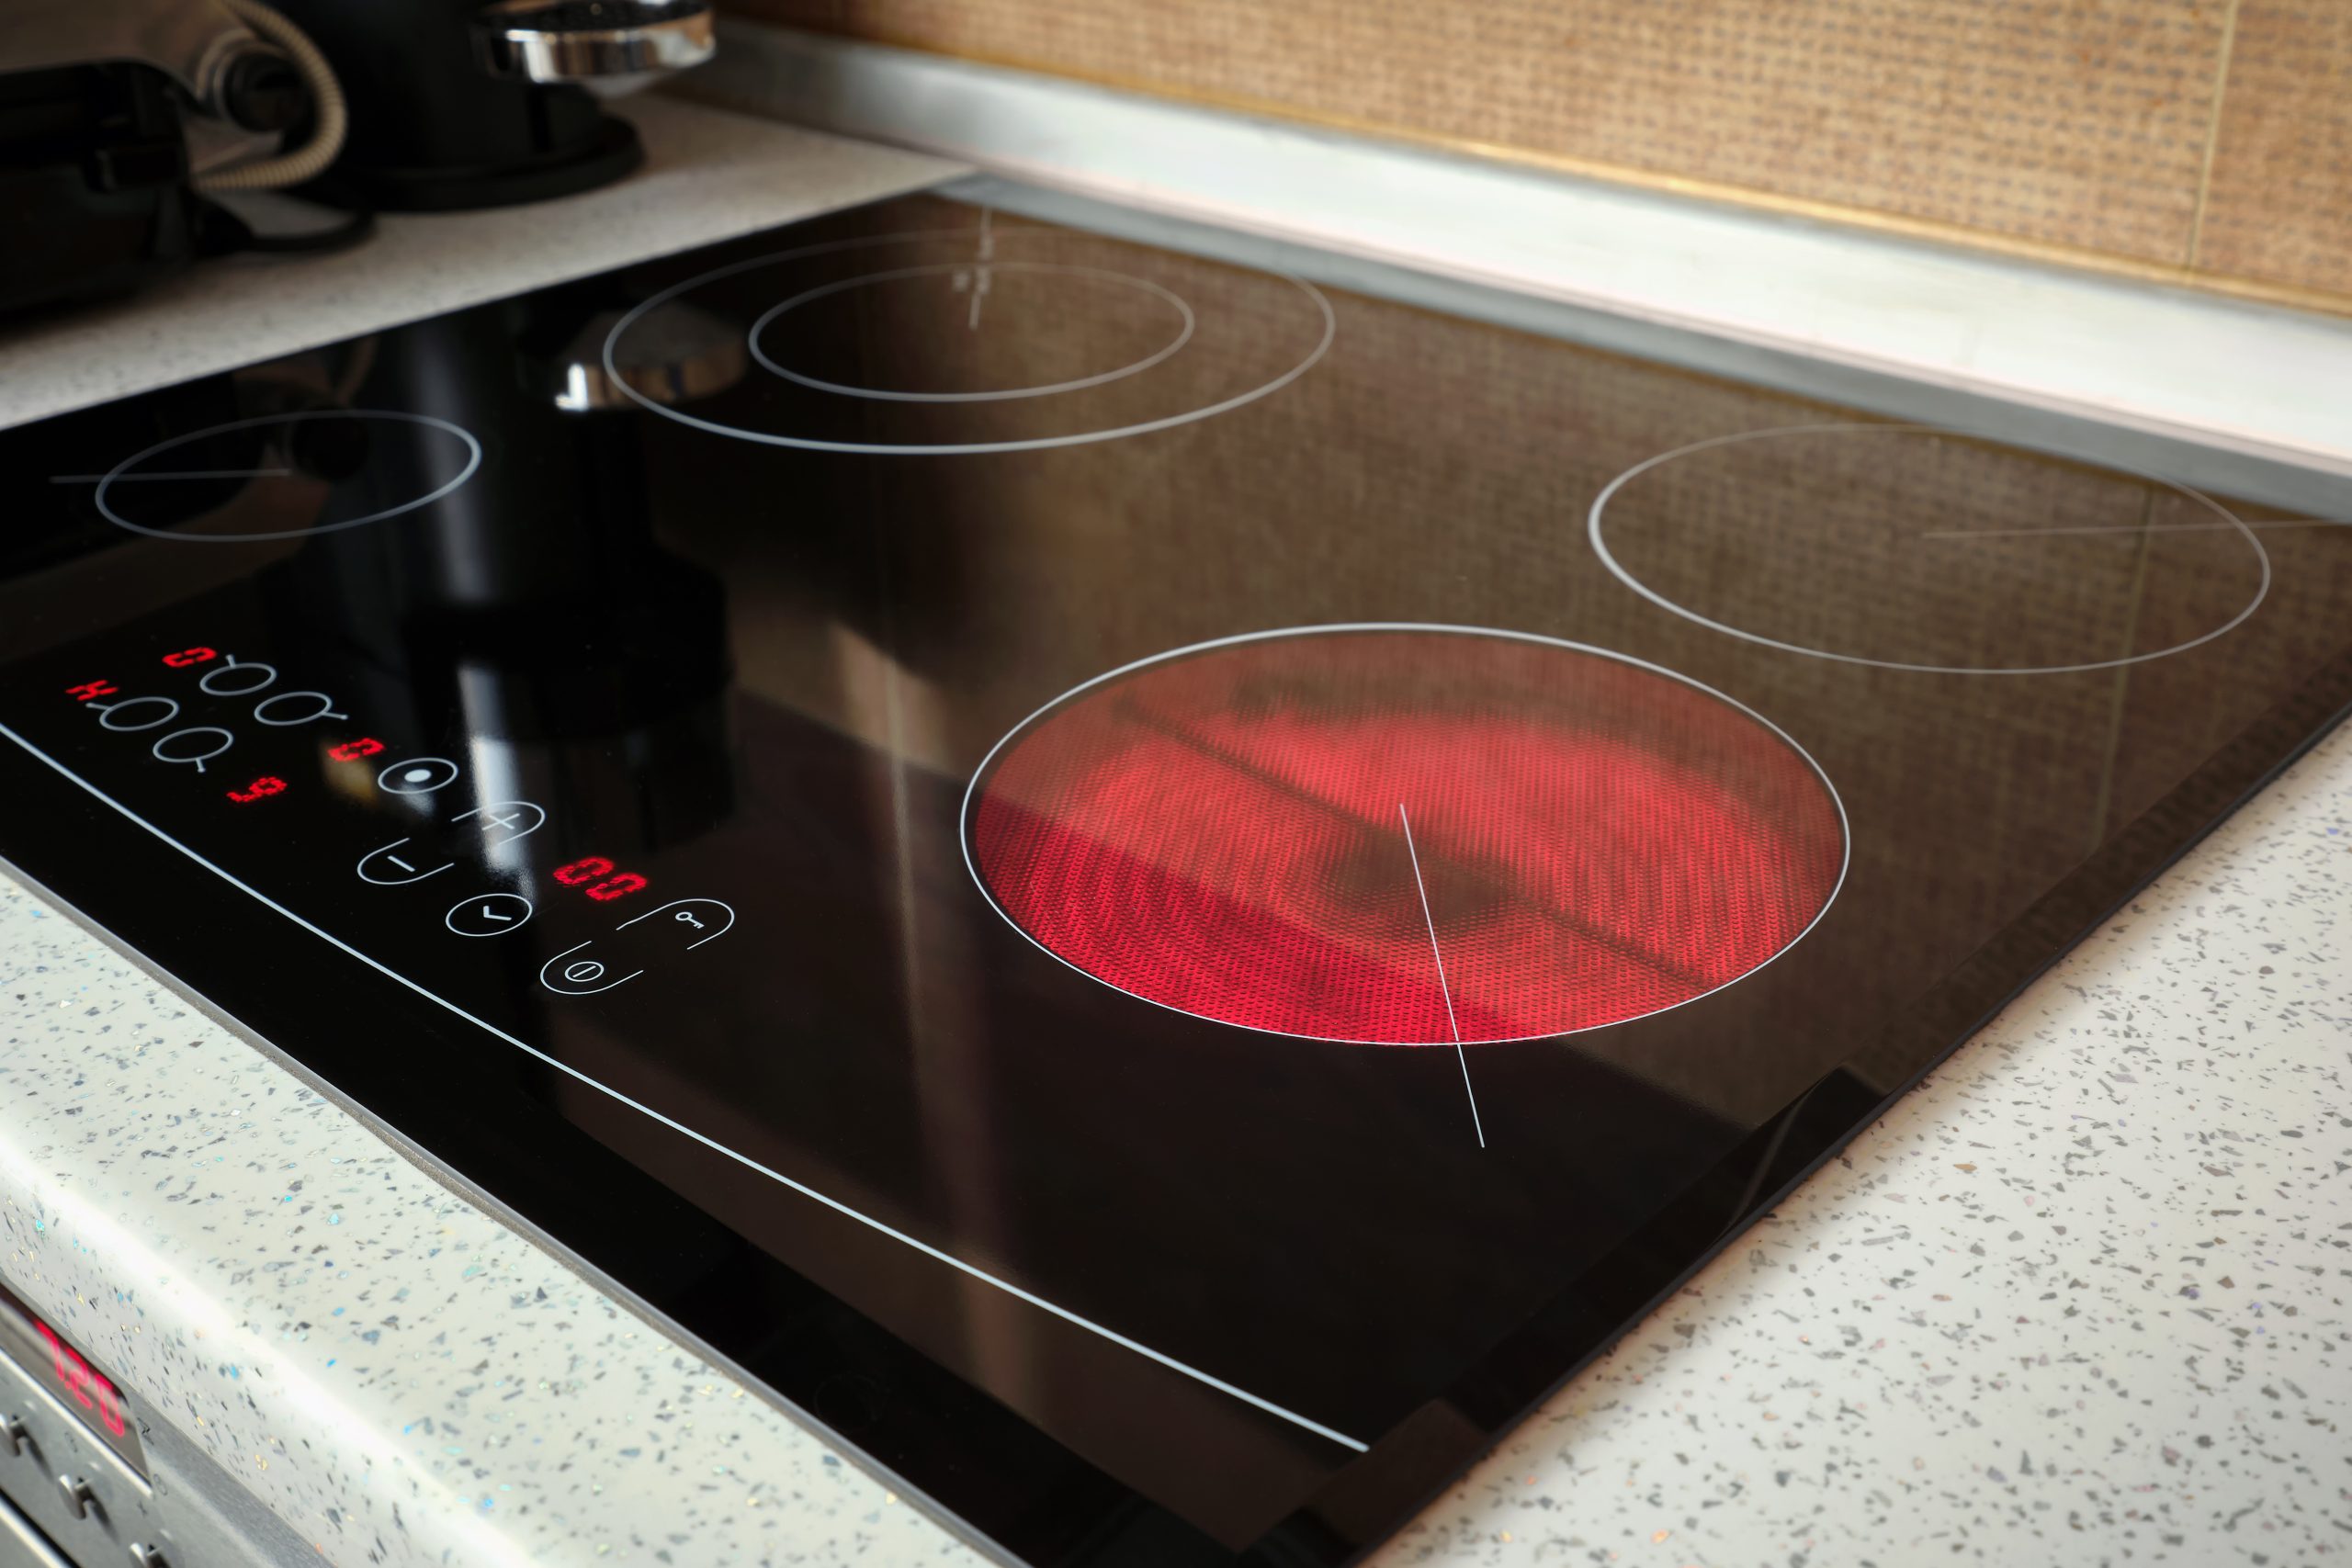
- ceramic hobGlass-ceramic cooktops are covered in many insurance policies. Whether your policy covers them depends on the wording, as not every glass insurance policy includes glass in furniture and appliances.
- Aquariums and terrariumsGlass from aquariums or terrariums can also be insured, but often only with an explicit agreement.
- Glass ceramics and special surfacesGlass panels from furniture, shower enclosures or mirrors may be included, depending on the tariff.
The crucial question is whether the damaged area falls under the definition of your policy terms and whether there is a break in the insured sense. This is precisely where insurers base their decisions when they reject a claim.
Is your ceramic cooktop cracked and your insurer won't pay? Have it checked whether it's covered by your glass insurance.
Typical exclusions and points of contention regarding glass
Even with existing glass protection, there are typical points of conflict:
- Scratches and chipsSuperficial damage without breakage is usually not covered by insurance. Whether a crack constitutes a break can be disputed in individual cases.
- Pre-existing damage and agingThe insurer sometimes argues that the damage is due to material fatigue. Whether this argument holds water depends on the evidence.
- Uninsured itemsMobile phone displays, glasses or optical lenses are regularly excluded from classic glass insurance.
Whether an exclusion applies is often a question of... Contract interpretation and breaches of duty. Unclear clauses are interpreted against the insurer.
Is the insurer invoking an exclusion clause? Have it checked whether the clause is even unambiguous.
Bicycle theft: what conditions trigger the benefit
Bicycle theft is covered by home contents insurance or a specific bicycle insurance policy. Whether and how much is paid out depends on several conditions, which often lead to disputes in the event of a claim:
- Locking and securingMany policies require that the bicycle was secured with a standard or explicitly agreed-upon lock. If this proof is lacking, the insurer will reduce or deny the claim.
- Nighttime clauseOlder household insurance policies only cover theft outside locked rooms during the day, not at night. If this clause is included, coverage for nighttime theft is void.
- Compensation limit: Under home contents insurance, the bicycle is often only replaced up to a percentage of the sum insured, unless a higher sum has been agreed upon.
- Proof and notificationYou must report the theft to the police and provide proof, such as a receipt and frame number.
Those who are aware of these requirements can secure their claim from the outset. Conversely, blanket rejections are often contestable if the insurer sets excessively high standards.
Was your bicycle stolen and is your insurer citing a clause? Have it checked whether the conditions for coverage are actually not met.
Household goods, bicycles and glass: the connection
Glass and bicycles are closely linked to home contents insurance. Bicycle insurance is often included as part of a home contents policy or is a separate policy, and glass damage can also be covered by home contents insurance or a separate glass insurance policy, depending on the contract.
Therefore, in the event of a claim, it's worth reviewing all relevant contracts. Sometimes, coverage exists through a component that wasn't even considered. Conversely, double insurance may exist, raising questions of jurisdiction.
Not sure which policy applies? Have your policies checked to determine which component covers the damage.
What you should do in case of glass or bicycle damage
In the event of damage in these sectors, proper documentation is crucial. These steps will help:
- Document the damagePhotograph the broken glass or the location of the bicycle theft and secure any evidence.
- Report theft: In case of bicycle theft, immediately report it to the police and keep the case number.
- Collect evidencePlease have your receipt, frame number, and, if applicable, information about the damaged area ready.
- Check conditionsClarify whether the damaged item is insured and what obligations apply.
- Have the rejection reviewed: Have any reduction or rejection measured against the specific clauses.
We cover how home contents insurance reacts after a burglary and how building insurance covers property damage in separate articles. You can find an overview of our work on our website. Lawyer specializing in building insurance and in the area Insurance law.
The sooner the damage is assessed, the better your claim can be secured. Have your rejection evaluated while the deadlines are still open.
Rogert & Ulbrich – Your lawyers in insurance law
Rogert & Ulbrich represent policyholders nationwide in disputes with their glass, bicycle, and household insurance companies. Attorney Dario Kovac, who is familiar with insurers' review and rejection strategies from his previous work on the insurers' side, serves as the contact person. We combine this insider knowledge with the firm's consumer protection experience from major cases in banking, capital markets, and automotive law. This allows us to engage with insurers on equal footing.
We review your policy and its terms, assign the claim to the correct category, and check whether exclusions or reductions are correctly applied. In the case of the Examination and enforcement of claims arising from insurance contracts We represent you out of court and, if necessary, in court. We involve any existing legal expenses insurance early on and obtain the coverage confirmation for you.
Has your glass or bicycle insurance company rejected or reduced your claim? Get in touch and secure your rights.